The Basic Economic Problem
From the The economic problems curriculum
TL;DR
The basic economic problem arises because human wants are unlimited, but the resources available to satisfy them are limited. This scarcity forces societies to make choices about what, how, and for whom to produce. Making these choices always involves an opportunity cost, which is the value of the next best alternative you give up.
1. The Mental Model
Think of it this way: you want everything, but you only have a limited amount of time, money, or stuff. Because you can't have it all, you have to choose, and every choice means giving up something else you wanted.
2. The Core Material
The basic economic problem is the fundamental challenge facing all societies: scarcity. It’s not just about money; it's about the limited availability of resources relative to unlimited wants.
2.1 Unlimited Wants

Photo by Tim Mossholder on Pexels
Human wants are desires for goods and services that give us satisfaction. These wants are endless and constantly evolving. Once one want is satisfied, another usually takes its place. For example, you might want a new phone, then a new car, then a bigger house, and so on.
2.2 Limited Resources (Factors of Production)

Photo by NEOSiAM 18+ on Pexels
Resources, also known as factors of production, are the inputs used to produce goods and services. They are finite and cannot meet all wants. Economists categorize these into four main types:
- Land: Natural resources (e.g., oil, water, forests, actual land).
- Labor: Human effort, both physical and mental, used in production.
- Capital: Man-made resources used to produce other goods and services (e.g., factories, machinery, tools, infrastructure). Don't confuse this with financial capital (money).
- Enterprise (or Entrepreneurship): The ability of individuals to combine the other three factors of production, take risks, and innovate.
2.3 Scarcity and Choice
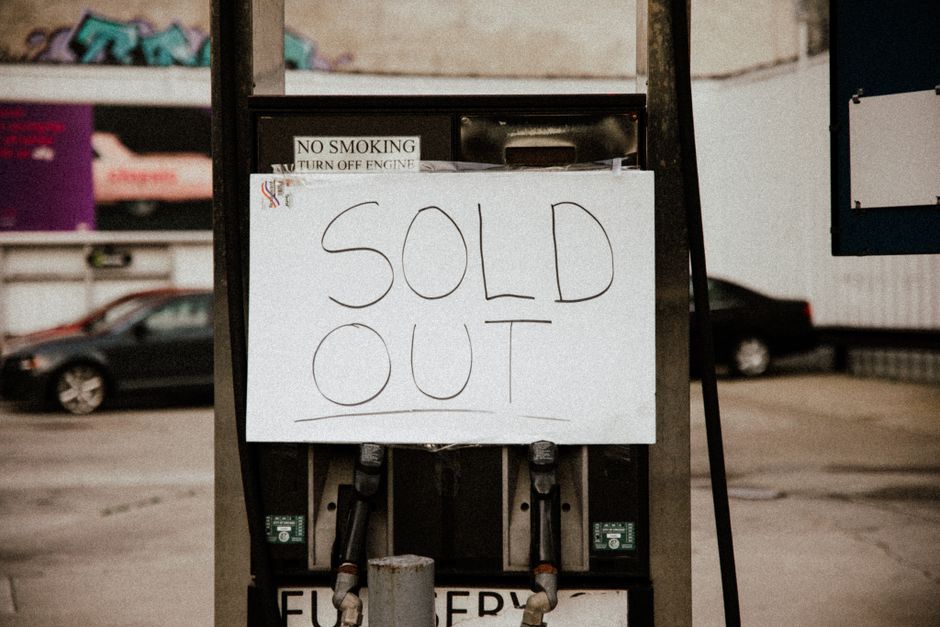
Photo by K on Pexels
Because wants are unlimited and resources are limited, scarcity exists. Scarcity means we can't have everything we want, so we must make choices. These choices are fundamental to economics. Every society, from individuals to entire nations, must decide:
- What to produce? (e.g., more healthcare or more education?)
- How to produce? (e.g., using more labor or more machinery?)
- For whom to produce? (e.g., who gets the goods and services produced?)
graph TD
    A["Unlimited Human Wants"] --> B["Limited Resources (Scarcity)"]
    B --> C{"Societies Must Make Choices"}
    C --> D["What to Produce?"]
    C --> E["How to Produce?"]
    C --> F["For Whom to Produce?"]
    C --> G["Opportunity Cost"]
    G --> H["Value of the Next Best Alternative Given Up"]
2.4 Opportunity Cost

Photo by Kindel Media on Pexels
When you make a choice due to scarcity, you automatically give up the next best alternative. This is called opportunity cost. It's the real cost of any decision. For example, if you choose to spend an hour studying economics, the opportunity cost might be the hour you could have spent working to earn money, or sleeping. It’s not necessarily about money; it's about the value of what you sacrifice.
3. Worked Example
Imagine a small island nation with limited resources – a certain amount of fertile land, a fixed number of workers, and some basic tools. The people on the island primarily need food (rice) and shelter (simple huts).
Scenario: The islanders can use all their resources to produce 100 units of rice OR 50 units of huts OR some combination.
Let's say they decide to produce 70 units of rice.
To produce those 70 units of rice, they have to divert resources (land, labor, tools) away from building huts. If they could have produced 50 units of huts by focusing entirely on huts, and now they are producing only 20 units of huts (because resources are shifted to rice production), then the opportunity cost of producing those 70 units of rice is 30 units of huts (50 maximum huts - 20 actual huts).
Conversely, if they decided to produce 30 units of huts, their opportunity cost would be the amount of rice they could have produced but didn't because resources were used for huts. If producing 30 huts means they can now only produce 40 units of rice, and their maximum rice production was 100 units, then the opportunity cost of those 30 huts is 60 units of rice (100 maximum rice - 40 actual rice).
This example highlights that every choice has a trade-off, and the true cost isn't just what you spend, but what you give up.
4. Key Takeaways
- Scarcity is the core economic problem, arising from unlimited wants versus limited resources.
- Resources, or factors of production, are categorized as land, labor, capital, and enterprise.
- Every society must answer "what, how, and for whom" to produce due to scarcity.
- Opportunity cost is the value of the next best alternative given up when a choice is made.
- Understanding scarcity helps explain why choices are necessary in economics.
- Economic decisions always involve trade-offs because resources are finite.
- The basic economic problem applies to individuals, businesses, and governments alike.
Common mistakes you should avoid:
- Confusing scarcity with poverty; scarcity means there aren't enough resources for everyone to have everything they want, not necessarily that there aren't enough basic necessities.
- Thinking opportunity cost is always about money; it's about the value of the next best alternative.
- Believing that technological advancements eliminate scarcity; while they can reduce it for some goods, they often create new wants or require new scarce resources.
- Forgetting that enterprise/entrepreneurship is a factor of production, not just land, labor, and capital.
5. Now Try It
Think about a recent significant purchase you made, like a new phone or a video game console. Spend 15 minutes listing:
1. Your unlimited wants at that time (what else did you want?).
2. The limited resources you had (money, time, etc.).
3. The specific choice you made (the purchase).
4. The opportunity cost of that purchase (what was the single next best thing you gave up by making that choice?).
Success means clearly identifying your choice and articulating what you directly gave up instead of another valued option.
Frequently asked about The Basic Economic Problem
Study this next
Get the full The economic problems curriculum
Clone the complete plan to your dashboard for unlimited AI-generated notes, practice quizzes, and a personalised revision schedule.
Save this course free