Solutions to the Basic Economic Problem
From the The economic problems curriculum
TL;DR
Every society faces the basic economic problem of scarcity, meaning unlimited wants with limited resources. Different economic systems — traditional, command, market, and mixed — offer varying solutions to decide what, how, and for whom to produce. Understanding these systems helps explain how resources are allocated and goods are distributed in the real world.
1. The Mental Model
Imagine a group of friends with a single pizza (limited resource) but everyone wants a whole pizza (unlimited wants). How do they decide who gets a slice, how many slices, and what toppings are on those slices? That's the basic economic problem, and different systems are like different rules for sharing that pizza.
2. The Core Material
The Basic Economic Problem is that human wants are unlimited, but the resources available to satisfy these wants are limited. This forces societies to make choices about:
1. What to produce? (e.g., more food or more weapons?)
2. How to produce? (e.g., with machines or human labor?)
3. For whom to produce? (e.g., who gets the goods and services?)
Different economic systems provide frameworks to answer these questions:
Traditional Economy
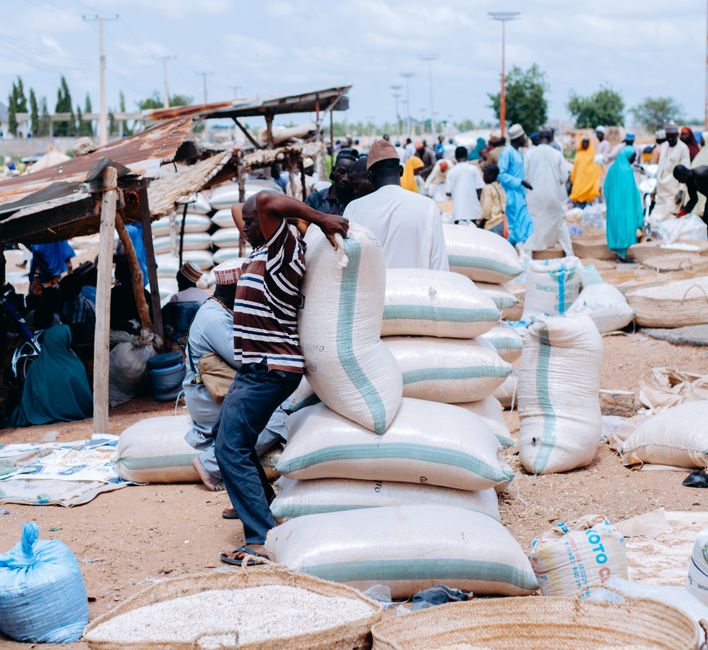
Photo by Moh DIKKO Photography on Pexels
Decisions are based on custom, habit, and tradition. Roles are often passed down through generations.
* What: What's always been produced.
* How: How it's always been produced.
* For whom: For whom it's always been produced (e.g., within families or specific social groups).
* Pros: Stable, predictable.
* Cons: Resistant to change, lower standard of living, less innovation.
Command Economy (Planned Economy)
Photo by Lukas Blazek on Pexels
The government or a central authority makes all economic decisions.
* What: Decided by central planners.
* How: Decided by central planners.
* For whom: Decided by central planners based on social goals.
* Pros: Can quickly mobilize resources for large-scale projects, income equality can be a goal.
* Cons: Lack of consumer choice, inefficiency, lack of innovation, shortages/surpluses.
Market Economy (Free Market Economy)
Photo by Alesia Kozik on Pexels
Economic decisions are made by individuals and businesses, driven by supply and demand and the pursuit of self-interest. There's minimal government intervention.
* What: Consumers' demand (purchases) signal to producers what to make.
* How: Producers choose the most efficient methods to maximize profit.
* For whom: Those who can afford to buy the goods and services (income determines purchasing power).
* Pros: Efficiency, innovation, consumer choice, high standard of living.
* Cons: Income inequality, potential for market failure (e.g., monopolies, public goods), boom-and-bust cycles.
Mixed Economy
Photo by Gosia K on Pexels
Most real-world economies are mixed, combining elements of market and command systems. The government plays a role (e.g., providing public goods, regulating markets) while market forces still drive most production and consumption.
* What, How, For Whom: Market forces generally dominate, but government intervenes to correct market failures, redistribute income, or provide essential services.
* Pros: Balances efficiency with equity, can provide a safety net.
* Cons: Can suffer from inefficiencies of both systems, finding the right balance is difficult.
Here's how these systems compare in their approach:
graph TD
    A["Basic Economic Problem: Scarcity"] --> B{"How to solve it?"}

    B --> C["Traditional Economy"]
    C --> C1["Based on custom/habit"]

    B --> D["Command Economy"]
    D --> D1["Central authority decides"]

    B --> E["Market Economy"]
    E --> E1["Individual choices, supply/demand"]

    B --> F["Mixed Economy"]
    F --> F1["Market + Government intervention"]
3. Worked Example
Imagine a newly discovered island nation, "Isla Fuerte," needs to decide how to allocate its resources for its primary industry: coconut harvesting.
- Traditional Approach: Villagers continue to harvest coconuts as their ancestors did, using hand-woven baskets and climbing trees. The harvest is shared among families based on historical claims and needs. Innovation is low, but everyone knows their role.
- Command Approach: The government of Isla Fuerte establishes a Coconut Planning Committee. They issue directives on how many coconuts each village must harvest, distribute climbing equipment, and dictate that all coconuts be sent to a central processing plant, from which they are then rationed to citizens. Production targets might be met, but there could be surpluses in some areas and shortages in others, and villagers have no say.
- Market Approach: Individual coconut farmers own their land and trees. They decide how many coconuts to harvest based on the price they can get in the market. They invest in better climbing gear or processing equipment if it helps them make more profit. Consumers who can pay the market price get coconuts. There's innovation and variety, but some poor islanders might not afford many coconuts.
- Mixed Approach: The government allows private coconut farmers to operate and sell their coconuts in the market (market forces). However, it sets environmental regulations for harvesting, provides subsidies to ensure small farmers can compete, and runs a food bank for those who can't afford coconuts (government intervention).
4. Key Takeaways
- The basic economic problem is universal: unlimited wants vs. limited resources.
- Every society must answer what, how, and for whom to produce.
- Traditional economies rely on custom and history for economic decisions.
- Command economies have a central authority making all economic choices.
- Market economies are driven by individual choices, supply, and demand.
- Most real-world economies are mixed, blending market freedom with government intervention.
- Each system has trade-offs regarding efficiency, equity, and innovation.
Common mistakes to avoid:
- Confusing a mixed economy with just a "slightly less market" economy; it’s a deliberate blend.
- Thinking one system is always inherently "best" without considering societal goals.
- Underestimating the role of scarcity as the root cause of all economic problems.
- Forgetting that the "what, how, for whom" questions apply to all economic systems.
5. Now Try It
Think about your own country or a country you're familiar with. Spend 15 minutes identifying examples of how it answers the "what, how, and for whom to produce" questions. Which economic system (or blend of systems) best describes its approach? For instance, think about healthcare, education, or food production. What role does the government play versus individual businesses and consumers?
Success looks like: You can point to specific policies or practices and explain whether they're more characteristic of a market, command, or traditional approach, and why.
Frequently asked about Solutions to the Basic Economic Problem
Study this next
Get the full The economic problems curriculum
Clone the complete plan to your dashboard for unlimited AI-generated notes, practice quizzes, and a personalised revision schedule.
Save this course free