Introduction to Economics as a Social Science
From the Economics Ch.1 curriculum
TL;DR
Economics is a social science that studies how people make choices when faced with scarcity. It's about understanding individual and societal decisions regarding resources. We use scientific methods to analyze these choices and their effects on society.
1. The Mental Model
Think of economics as the study of "not enough." We can't have everything we want, so we have to make choices. Economics helps us understand why we make those choices and what happens as a result.
2. The Core Material
Economics is fundamentally about how individuals, businesses, and governments make choices because resources are scarce. Scarcity means that there aren't enough resources (like time, money, natural resources) to satisfy all of our wants and needs. This forces us to prioritize and make trade-offs.
Scarcity and Choice
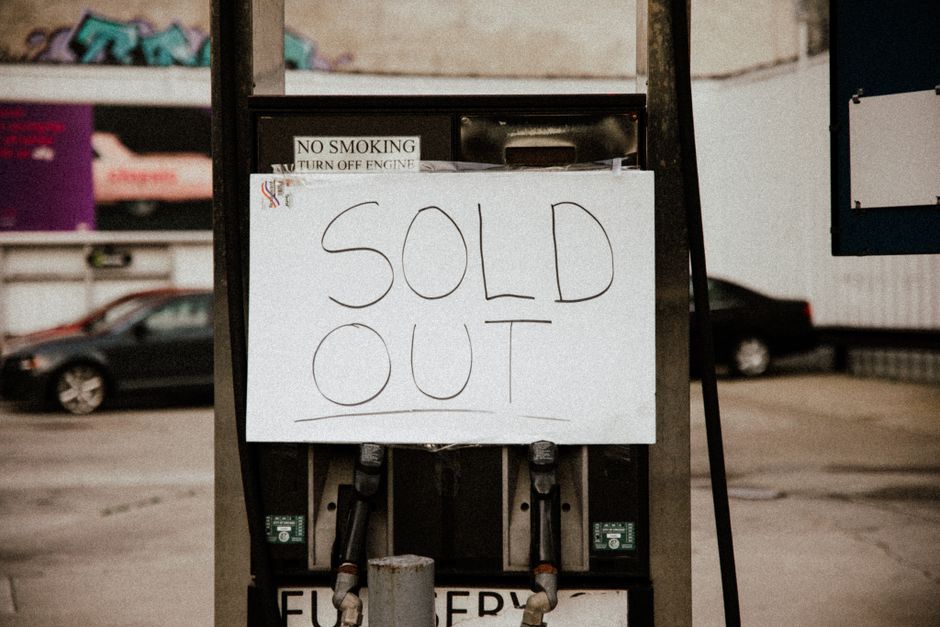
Photo by K on Pexels
The core problem in economics is scarcity. Because of scarcity, every choice has an opportunity cost – this is the value of the next best alternative you give up when you make a choice. For example, if you choose to study for an economics exam, the opportunity cost might be the fun movie you could have watched instead.
Microeconomics vs. Macroeconomics
Photo by Atlantic Ambience on Pexels
Economics is often divided into two main branches:
* Microeconomics: Focuses on the decisions of individual economic units, like households, firms, and individual markets. It asks questions like: How does a price change affect consumer demand for a product? How do firms decide how much to produce?
* Macroeconomics: Looks at the economy as a whole. It examines aggregate phenomena like inflation, unemployment, economic growth, and government policies. It asks questions like: What causes recessions? How can a government reduce unemployment?
Economics as a Social Science

Photo by Nataliya Vaitkevich on Pexels
Economics uses a systematic approach, similar to other sciences, to study human behavior. We develop theories and models to explain economic phenomena. These models are simplified representations of reality that help us understand complex relationships. We then use data to test these theories and see if they hold up in the real world. This scientific approach helps us predict outcomes and inform policy decisions.
Here's how the economic way of thinking generally flows:
graph TD
    A["Scarcity (Unlimited wants vs. Limited resources)"] --> B["Need for Choices"]
    B --> C["Trade-offs & Opportunity Cost"]
    C --> D["Economic Questions (What? How? For Whom?)"]
    D --> E["Formulate Theories/Models"]
    E --> F["Collect & Analyze Data"]
    F --> G["Evaluate & Refine Theories"]
    G --> H["Inform Policy Decisions"]
3. Worked Example
Let's say a local government has a budget of \$1 million. They can either build a new park or renovate an existing community center. Both are good for the community.
- Scarcity: The \$1 million budget is limited; it's scarce. They can't do both projects simultaneously.
- Choice: The government must choose between the park and the community center.
- Opportunity Cost: If they choose to build the new park, the opportunity cost is the renovated community center (and all its benefits, like better facilities for local groups). If they choose to renovate the community center, the opportunity cost is the new park. The government will weigh the benefits and costs of each option, considering factors like community demand, long-term impact, and maintenance costs, to make their decision.
4. Key Takeaways
- Economics is the study of how society manages its scarce resources.
- Scarcity is the fundamental problem that drives all economic decisions.
- Every choice has an opportunity cost, which is the value of the next best alternative given up.
- Microeconomics focuses on individual decisions; macroeconomics looks at the economy as a whole.
- Economists use scientific methods, including models and data analysis, to understand and predict economic behavior.
- Economics is a social science because it studies human behavior and interactions within society.
Common Mistakes to Avoid:
- Confusing wants with needs: In economics, wants are unlimited, but needs often refer to basic necessities.
- Forgetting about opportunity cost: Always think about what you're giving up when making a decision.
- Assuming "all else equal" (ceteris paribus) doesn't matter: Economic models often simplify reality by holding other factors constant, which is important to remember.
- Thinking that economics only applies to money: It applies to any resource where choices must be made due to scarcity, including time or even social relationships.
5. Now Try It
Think about a recent personal decision you made that involved limited resources. Identify the scarce resource, the choice you made, and the opportunity cost of that choice. Write down these three elements and be prepared to explain why it was an economic decision. Your success will look like clearly identifying each of those components for your personal example.
Frequently asked about Introduction to Economics as a Social Science
Study this next
Get the full Economics Ch.1 curriculum
Clone the complete plan to your dashboard for unlimited AI-generated notes, practice quizzes, and a personalised revision schedule.
Save this course free