Demand and Supply: The Basics of Market Interaction
From the intro to eco curriculum
TL;DR
Demand and supply are the fundamental forces that determine prices and quantities in a market economy. Demand represents what buyers are willing and able to purchase, while supply represents what sellers are willing and able to offer. Their interaction establishes the equilibrium price and quantity where both buyers and sellers are satisfied.
1. The Mental Model
Think of a market as a balancing scale. On one side, you have buyers (demand), and on the other, you have sellers (supply). The "price" is the pivot point, constantly adjusting until the scale balances, meaning the amount buyers want exactly matches the amount sellers offer.
2. The Core Material
In economics, demand and supply explain how markets operate. They're not just abstract ideas; they're about real people making real decisions.
Understanding Demand

Photo by Sebastian Maitre on Pexels
Demand refers to the quantity of a good or service that consumers are willing and able to purchase at various prices during a specific period. It's not just wanting something; you also need the money to buy it.
The Law of Demand states that, all else being equal (ceteris paribus), as the price of a good increases, the quantity demanded decreases, and vice versa. People generally buy less of something when it's expensive and more when it's cheap.
A demand curve is a graph that illustrates this inverse relationship, usually sloping downwards from left to right.
Factors that can shift the entire demand curve (meaning demand changes at every price point) include:
* Income: For most goods (normal goods), higher income means higher demand. For "inferior goods" (like cheap ramen), higher income might mean lower demand.
* Tastes and Preferences: If something becomes popular, demand increases.
* Prices of Related Goods:
* Substitutes: If the price of a substitute good (like coffee vs. tea) goes up, demand for the original good (tea) might increase.
* Complements: If the price of a complementary good (like hot dogs vs. hot dog buns) goes up, demand for the original good (hot dogs) might decrease.
* Expectations: If people expect prices to rise in the future, current demand might increase.
* Number of Buyers: More buyers in the market means higher overall demand.
Understanding Supply
Supply refers to the quantity of a good or service that producers are willing and able to offer for sale at various prices during a specific period. Producers are motivated by profit.
The Law of Supply states that, all else being equal, as the price of a good increases, the quantity supplied increases, and vice versa. Sellers want to sell more when they can get a higher price.
A supply curve is a graph that illustrates this direct relationship, usually sloping upwards from left to right.
Factors that can shift the entire supply curve include:
* Input Prices: If the cost of resources (labor, materials) goes up, supply decreases.
* Technology: Better technology usually means lower production costs and increased supply.
* Government Policies: Taxes can decrease supply; subsidies can increase it.
* Expectations: If producers expect future prices to rise, they might hold back some supply now to sell later.
* Number of Sellers: More sellers in the market means higher overall supply.
Market Equilibrium
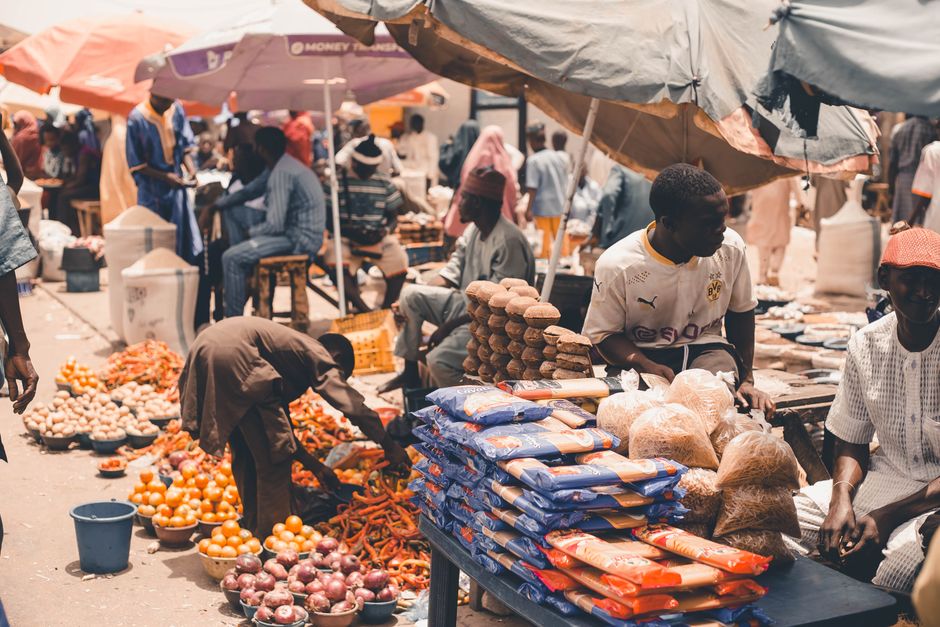
Photo by El'bataky photos on Pexels
Market equilibrium occurs at the point where the quantity demanded equals the quantity supplied. At this equilibrium price and equilibrium quantity, there's no pressure for the price to change because buyers want to buy exactly what sellers want to sell.
- If the price is above equilibrium, there's a surplus (quantity supplied > quantity demanded). Sellers will lower prices to clear excess stock.
- If the price is below equilibrium, there's a shortage (quantity demanded > quantity supplied). Buyers will bid up prices, and sellers will increase production.
Here's how these concepts link together:
graph TD
    A["Consumer Willingness & Ability (Demand)"] --> B{"Market Price"}
    C["Producer Willingness & Ability (Supply)"] --> B

    B -- "Price Too High" --> D["Surplus"]
    D --> E["Producers Lower Price"]
    E --> B

    B -- "Price Too Low" --> F["Shortage"]
    F --> G["Consumers Bid Up Price"]
    G --> B

    B -- "Quantity Demanded = Quantity Supplied" --> H["Equilibrium"]
3. Worked Example
Let's imagine the market for artisanal coffee beans in a small town.
Demand Schedule:
* At $15/bag, quantity demanded = 10 bags
* At $12/bag, quantity demanded = 20 bags
* At $9/bag, quantity demanded = 30 bags
* At $6/bag, quantity demanded = 40 bags
* At $3/bag, quantity demanded = 50 bags
Supply Schedule:
* At $15/bag, quantity supplied = 50 bags
* At $12/bag, quantity supplied = 40 bags
* At $9/bag, quantity supplied = 30 bags
* At $6/bag, quantity supplied = 20 bags
* At $3/bag, quantity supplied = 10 bags
By comparing the schedules, we can find the equilibrium:
| Price ($) | Quantity Demanded | Quantity Supplied | Outcome |
|---|---|---|---|
| 15 | 10 | 50 | Surplus (40) |
| 12 | 20 | 40 | Surplus (20) |
| 9 | 30 | 30 | Equilibrium |
| 6 | 40 | 20 | Shortage (20) |
| 3 | 50 | 10 | Shortage (40) |
The equilibrium price for artisanal coffee beans is $9 per bag, and the equilibrium quantity is 30 bags. At this price, the amount buyers want to buy matches exactly what sellers want to sell.
Now, imagine there's a new health report touting the benefits of coffee (a shift in tastes and preferences). Demand increases by 10 bags at every price.
New Demand Schedule:
* At $15/bag, quantity demanded = 20 bags
* At $12/bag, quantity demanded = 30 bags
* At $9/bag, quantity demanded = 40 bags
* At $6/bag, quantity demanded = 50 bags
* At $3/bag, quantity demanded = 60 bags
Comparing the new demand with the original supply:
| Price ($) | New Q Demanded | Original Q Supplied | Outcome |
|---|---|---|---|
| 15 | 20 | 50 | Surplus (30) |
| 12 | 30 | 40 | Shortage (new 10) |
| 12 | 30 | 40 | Surplus (10) |
| 9 | 40 | 30 | Shortage (10) |
This isn't quite right. Let's find the new equilibrium with the shifted demand.
The new demand: (15,20), (12,30), (9,40), (6,50), (3,60)
The old supply: (15,50), (12,40), (9,30), (6,20), (3,10)
Looking for where New Q Demanded = Original Q Supplied:
| Price ($) | New Q Demanded | Original Q Supplied |
|---|---|---|
| 15 | 20 | 50 |
| 12 | 30 | 40 |
| 9 | 40 | 30 |
| 6 | 50 | 20 |
Ah, the demand increase moved the equilibrium. At $9, there's now a shortage of 10 (40 demanded vs 30 supplied). This will push the price up. Let's check the next price point.
If the market adjusts:
* At $12: New Q Demanded = 30. Original Q Supplied = 40. Now there's a surplus of 10. The price would fall back down.
This indicates the new equilibrium price is somewhere between $9 and $12, and the quantity somewhere between 30 and 40. This is where linear equations would help, but we're doing basics. The key takeaway is that an increase in demand, with unchanging supply, leads to a higher equilibrium price and a higher equilibrium quantity (if the supply curve can extend). In this discrete example, if the quantities were exactly linear, we'd need to find the intersection. For simplicity, let's assume the price moves up to $12 where there's still more supply than demand (40 supplied vs 30 demanded). The market will adjust.
If we had linear equations, we'd solve for it directly. With discrete tables, it shows the direction of pressure. The increase in demand means consumers now demand 40 units at the old equilibrium price of $9, while suppliers still offer 30. This creates a shortage, pushing prices up until a new balance is found. The example shows that the new equilibrium price would be higher than $9 and the new quantity higher than $30.*
Let's adjust the original demand shift to make it land on a discrete point for this example. Suppose the demand shifts such that at $12, new quantity demanded is 40. Then:
New Demand Schedule (revised for clarity):
* At $15/bag, quantity demanded = 30 bags
* At $12/bag, quantity demanded = 40 bags
* At $9/bag, quantity demanded = 50 bags
Comparing revised new demand with original supply:
| Price ($) | Revised New Q Demanded | Original Q Supplied | Outcome |
|---|---|---|---|
| 15 | 30 | 50 | Surplus (20) |
| 12 | 40 | 40 | Equilibrium |
| 9 | 50 | 30 | Shortage (20) |
Now the new equilibrium price is
Frequently asked about Demand and Supply: The Basics of Market Interaction
Study this next
Get the full intro to eco curriculum
Clone the complete plan to your dashboard for unlimited AI-generated notes, practice quizzes, and a personalised revision schedule.
Save this course free